Why a valuable estate can still run short of cash
When people hear the word estate, they often think of property, investments and business shares. Those assets may be worth millions, but value on paper is not the same as cash in hand. If the estate has to settle fees, taxes, debt and administration costs before assets can be transferred, the family may face a shortfall.
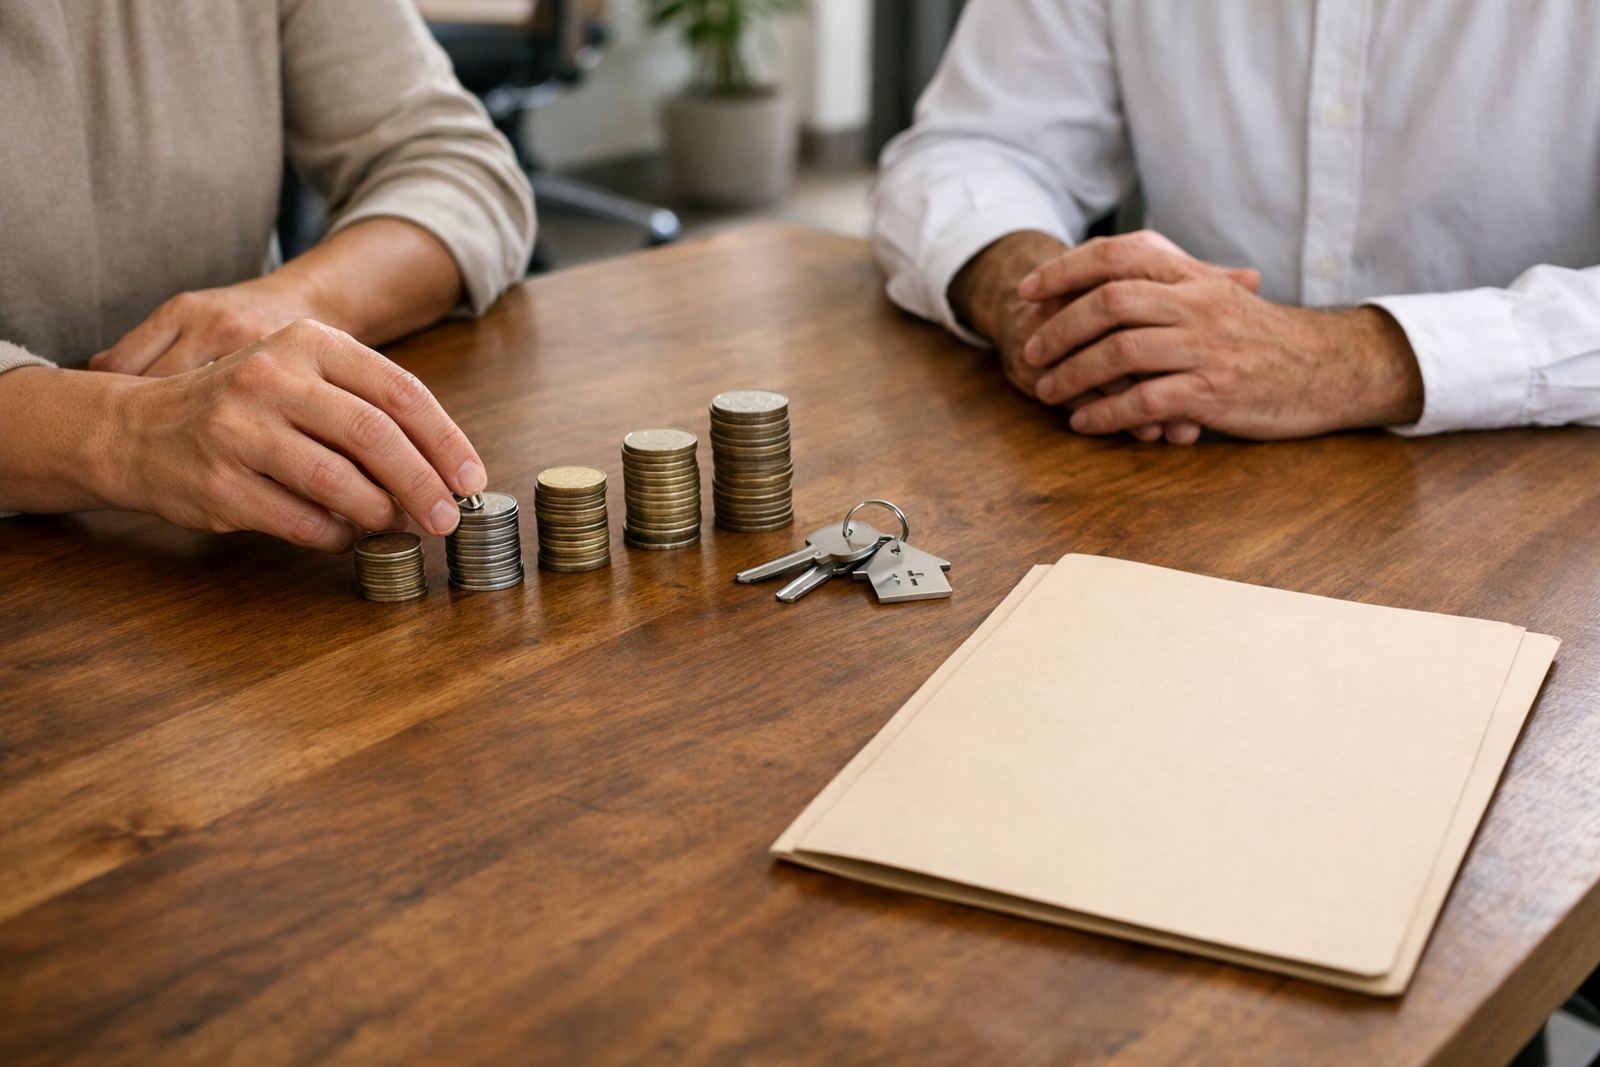
This is what estate liquidity means: the ability of an estate to meet its immediate obligations without forcing a rushed sale of assets. A family home in Stellenbosch, a rental unit in Paarl or a shareholding in a business can all be valuable, but they cannot always be turned into money quickly. If there is no available cash or near-cash asset, the executor may have to wait, borrow or sell under pressure. That is where good planning matters.
Many South African families are surprised by how many costs arrive at once. Funeral expenses, outstanding accounts, transfer costs, executor fees and tax related items can all land before the final distribution. Even when the estate is orderly, the timing can be tight.
What creates a liquidity gap in South African estates
Liquidity problems usually happen when the estate is structured around growth rather than access. A person may have built wealth through property, a business or long-term investments, but not kept enough cash aside for the final bill. It is a common situation for entrepreneurs, family businesses and homeowners who have paid off property but keep limited liquid funds.
- Most wealth is tied up in immovable property or a business interest.
- Investments are long-term and not easy to realise without penalties.
- There is debt on the home, vehicle finance or business borrowing.
- Executor fees, conveyancing costs and admin charges must be paid first.
- There may be delays from missing documents or unclear beneficiary instructions.
In South Africa, the pressure can be greater where assets are spread across different provinces or where a family member lives overseas. A coastal property in Durban, for example, may take time to value and transfer, while a business in Johannesburg may still need working capital to keep trading. If the estate has to sell at the wrong time, the family can lose value that took years to build.
How liquidity affects the executor and the family
The executor’s job is to collect assets, pay liabilities and distribute the balance in line with the will or intestate law. That sounds simple, but cash flow can make it difficult. Banks may freeze accounts, property cannot be sold instantly, and some assets only realise value after an extended process. Until then, the estate still has bills.
For the family, this can create stress at the exact time they need calm. A surviving spouse may be waiting for funds to cover school fees or medical aid contributions. Adult children may be trying to keep a household going while the estate is being finalised. If there is no liquidity plan, the family can be forced into short term borrowing or an unwanted sale of assets, which adds pressure and may weaken the overall legacy.
A practical estate plan should not only ask, “Who gets what?” It should also ask, “How will the estate pay its way in the meantime?” That one question changes the shape of the plan.
Simple ways to improve estate liquidity before it is needed
Liquidity planning is not about holding large amounts of idle cash. It is about making sure there is enough accessible value to cover the first wave of estate costs and keep key obligations on track. A balanced plan can protect the family without undoing the wider wealth strategy.
- Keep a portion of the estate in liquid investments or cash equivalents.
- Review beneficiary nominations so selected assets pass quickly where possible.
- Check whether life cover can provide cash for estate costs and debt.
- Map all assets, debts and ownership structures in one place.
- Align the will with trust deeds, business agreements and retirement benefits.
It also helps to test the estate with a simple question: if the main asset could not be sold for six months, would there still be enough cash to carry the estate through? If the answer is no, the plan needs adjusting. That may mean changing how assets are held, setting aside cash reserves, or using insurance in a measured way to create immediate funding.
A Stellenbosch example: asset rich but cash poor
Consider a family in Stellenbosch with a primary home, a small vineyard interest, retirement savings and a share in a logistics business. On paper the estate is strong. In practice, the bulk of the value sits in property and equity that cannot be accessed on day one. When the owner passes away, the estate must still meet funeral costs, legal fees and ongoing household expenses.
If there is also a bond balance and business debt, the liquidity gap becomes more visible. The executor may need to preserve the value of the vineyard interest while the family waits for the estate to clear. Without a plan, the pressure can force a sale of the wrong asset at the wrong time. With proper structuring, the family can use a mix of cash reserves, life cover and clean succession steps to keep things steady.
This is where estate planning and retirement planning meet. A well thought out structure can give the surviving spouse or children time, not panic. It can also protect business continuity, which matters when employees and trading partners depend on order after a founder dies.
How to build a cleaner legacy with less pressure
The best time to address liquidity is while the owner is still healthy and in control. That allows the family to talk through priorities, not just paperwork. It also makes it easier to compare the estate cost against the cash that is actually available.
A good review should cover the will, trust arrangements, investment accounts, retirement benefits and business interests. It should also include beneficiary reviews, asset mapping and a liquidity analysis. For many families, a short trustee briefing or family meeting clears up years of confusion in one session. That is often more useful than adding more products.
Estate liquidity is not a technical extra. It is part of making sure wealth moves with purpose and not under duress. If you want the next generation to inherit more than assets, the plan must allow the estate to function when the time comes. A calm structure today can save a great deal of strain later, and probably a few costly mistakes too.