What an Asset Consolidation Plan actually does
An Asset Consolidation Plan is a practical review and restructuring process for families with money spread across several accounts, trusts, businesses, policies and property holdings. The aim is not to rush everything into one pot, but to group assets in a way that makes administration easier, supports estate planning and reduces the chance of confusion later on.
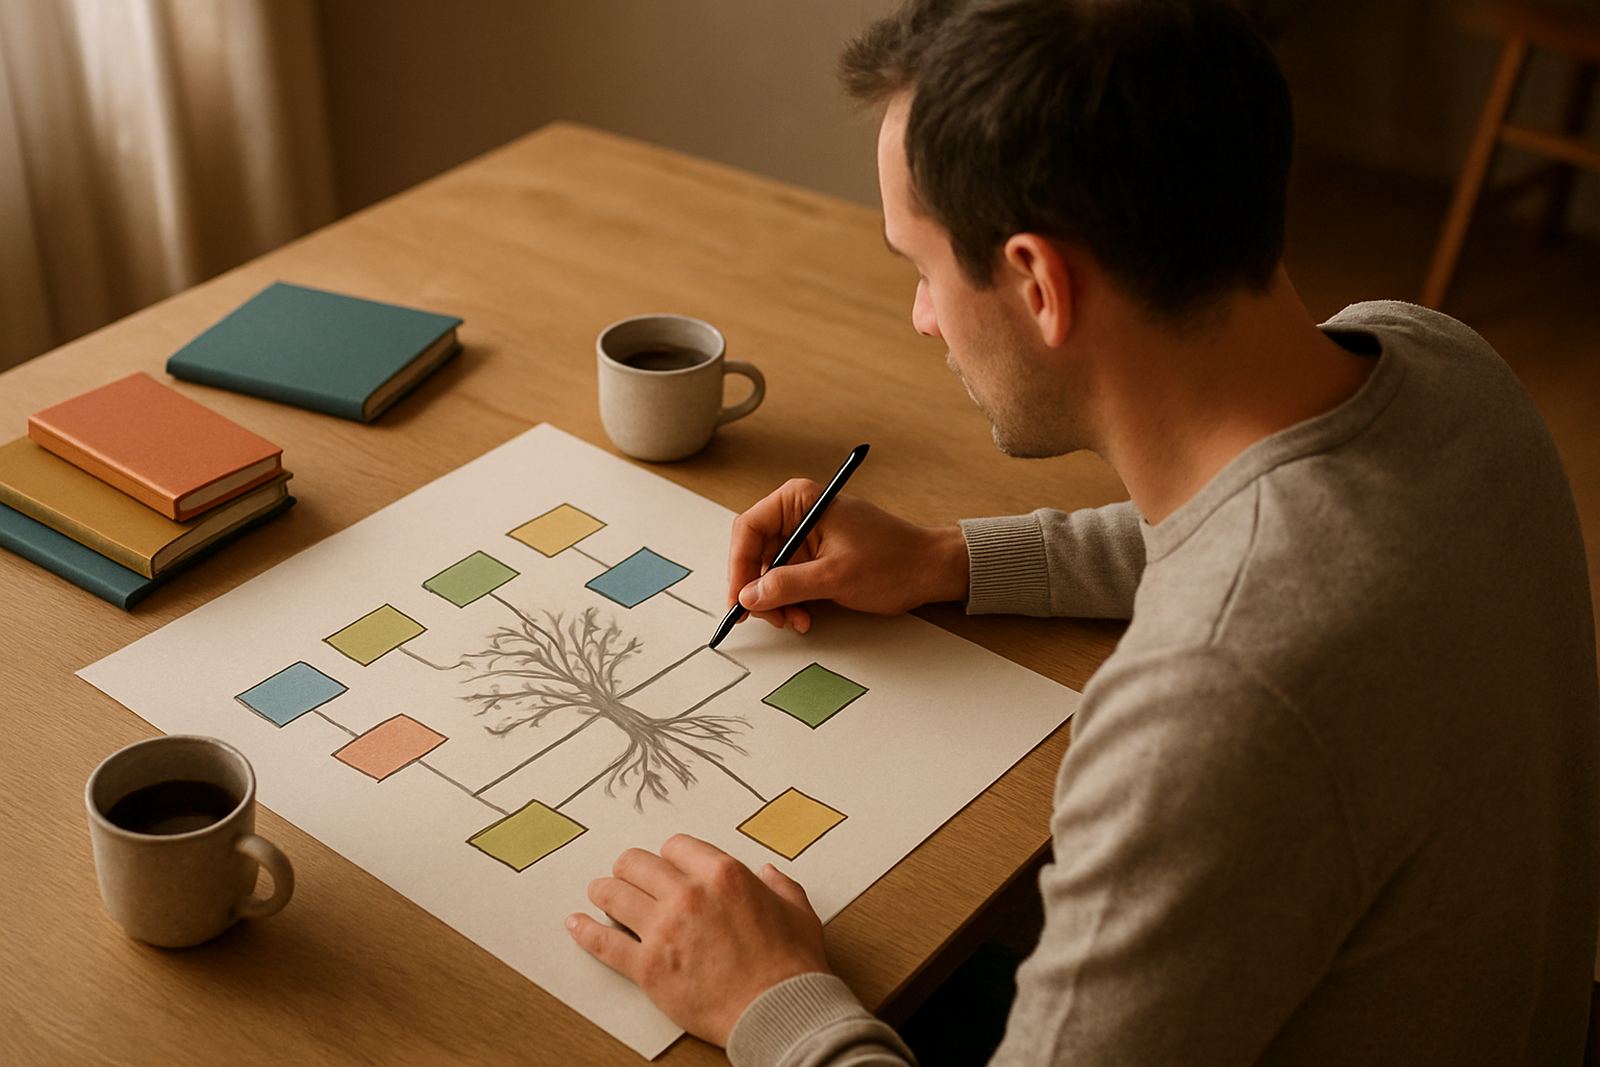
We start by mapping each holding, who controls it, who benefits from it and how it will move on death or incapacity. That may include bank accounts, share portfolios, retirement funds, business interests, loan accounts, fixed property, family trust assets and policy proceeds. Once everything is visible, we can point out gaps, duplication and items that may create delay for heirs or co-owners.
For many clients, the benefit is simple: fewer loose ends. A good consolidation plan gives you a clearer picture of cash flow, ownership and liquidity, while keeping the family informed. It is especially useful where there are children from different relationships, multiple properties, or a business that needs to keep trading if something happens to the owner.
Plan sizes and structure options
There is no one-size-fits-all setup. The right structure depends on the number of assets, the family make-up, the size of the estate and how much ongoing administration you are prepared to handle. Some clients need a light review with a few transfers and document updates. Others need a fuller restructure with trust review, succession steps and regular beneficiary checks.
- Starter review: up to 5 core holdings, suitable for straightforward family estates and one primary residence.
- Family structure plan: 6 to 12 holdings, often including a trust, retirement funds and one or two businesses.
- Complex legacy plan: 12 plus holdings, multiple beneficiaries, cross-border links or layered family arrangements.
- Business owner plan: built around ownership continuity, key person risk and liquidity for taxes, debt and transfer costs.
We also consider how assets are registered, whether they sit in personal names or legal entities, and whether the family wants control kept central or spread between trustees and co-directors. In some cases, consolidating means simplifying the paperwork without changing ownership. In others, it means changing the structure itself so the family can manage it more cleanly over time.
Where it suits best in South African families
This plan works well for Stellenbosch families, Cape Town professionals, Paarl business owners and Johannesburg or Durban households that have built wealth over time through property, trading businesses and long-term investments. It also suits families who live in different provinces and need one clear plan that can be discussed by video consultation.
It is particularly useful when there are assets sitting in different places with no single person holding the full picture. That might be a farm share in the Boland, an investment account in Gauteng, a retirement benefit from earlier employment and a family trust used for education costs. If no one can explain the full picture quickly, the estate will probably take longer than it should.
For business owners, consolidation can help separate personal and business wealth, which makes succession conversations much easier. For multi-generational households, it can show which assets are meant to produce income now, and which ones are there for the next generation. That clarity matters when family members expect different things from the same estate.
What is included in the review and setup
Every consolidation plan starts with a full asset map. We gather documents, check beneficiary nominations, review ownership and test how the structure will behave if someone dies, becomes incapacitated or wants to retire. Where needed, we arrange family meetings so everyone understands the current position before decisions are made.
- Asset mapping across personal, trust and business holdings
- Liquidity analysis for estate costs, tax and transfer expenses
- Will coordination and beneficiary review
- Trust structuring checks and trustee briefing support
- Succession facilitation for business and family wealth
- Plan review with practical next steps and responsibilities
We also look at whether there is too much overlap between holdings, for example duplicated insurance cover or separate accounts that could be consolidated for simpler record keeping. Sometimes the answer is not to move anything immediately, but to fix the instructions attached to the assets. That can save time and prevent family disputes later on.
Installation, paperwork and moving parts
There is no physical installation, but there is a process to follow carefully. Changes may involve signed instructions, trustee resolutions, updated beneficiary nominations, new account documentation, certified identity copies and supporting estate papers. Where a trust or company is involved, the paperwork must match the legal authority of the people signing it.
In practical terms, the process can take a few weeks for a simple structure, and several months for a more involved estate. Delays usually happen when records are missing, title deeds are old, or a family has not agreed on who should control what. We help reduce those delays by setting out the sequence clearly and keeping one point of contact where possible.
There are no power or gas needs for this service, but there is a real admin requirement: current documents, clean records and access to family decision makers. If the family lives in different places, online meetings are usually the easiest route. For coastal clients, we also watch for older paper records that may have been damaged by humidity, damp or storage issues over time.
Care, servicing and keeping the plan current
A consolidation plan should not be treated as a once-off file that sits in a drawer. Families change, businesses change and tax or legal rules can shift. We recommend a regular review so the structure still matches the family situation and the intended heirs.
Good servicing includes checking for births, deaths, marriages, divorces, new business interests, loan account changes and updated trustee details. It is also sensible to review the plan after a property purchase, a major sale, or when a child becomes financially independent. If the family has trustees or executors who are not active in day to day matters, a short briefing each year helps keep everyone aligned.
For many clients, annual reviews work well. Others prefer to review after any major life event. Either way, the point is to keep the structure useful, not let it drift. A plan that was correct five years ago may now be holding the wrong balance between access, control and protection.
What to check before you order
Before starting, it helps to know what you own, who currently controls each item and what problem you want the consolidation to solve. Some families want lower admin. Others want a clearer legacy path, better liquidity or fewer disputes. The more direct the brief, the easier it is to shape the right plan.
- List all assets, including property, business interests, trusts and investments
- Confirm current beneficiaries and executor or trustee details
- Check whether any asset has debt attached to it
- Bring any existing wills, trust deeds and company records
- Note family relationships that may affect succession or control
- Identify whether the plan is for control, simplicity, or both
Families often underestimate how much time is saved when the records are finally brought together. One clean plan can prevent repeated calls, duplicate paperwork and late surprises. It also makes it easier for advisers, trustees and family members to work from the same facts, instead of guessing.
Key facts
| Service type | Asset consolidation and legacy planning review |
|---|---|
| Typical scope | 5 to 12 plus holdings depending on family complexity |
| Best suited for | Families, entrepreneurs and business owners |
| Delivery | In person in Stellenbosch and nearby areas, plus video consultations nationwide |
| Key outputs | Asset map, liquidity review, beneficiary check and action plan |
| Review cycle | Annual, or after a major life or business change |