What an asset map actually shows
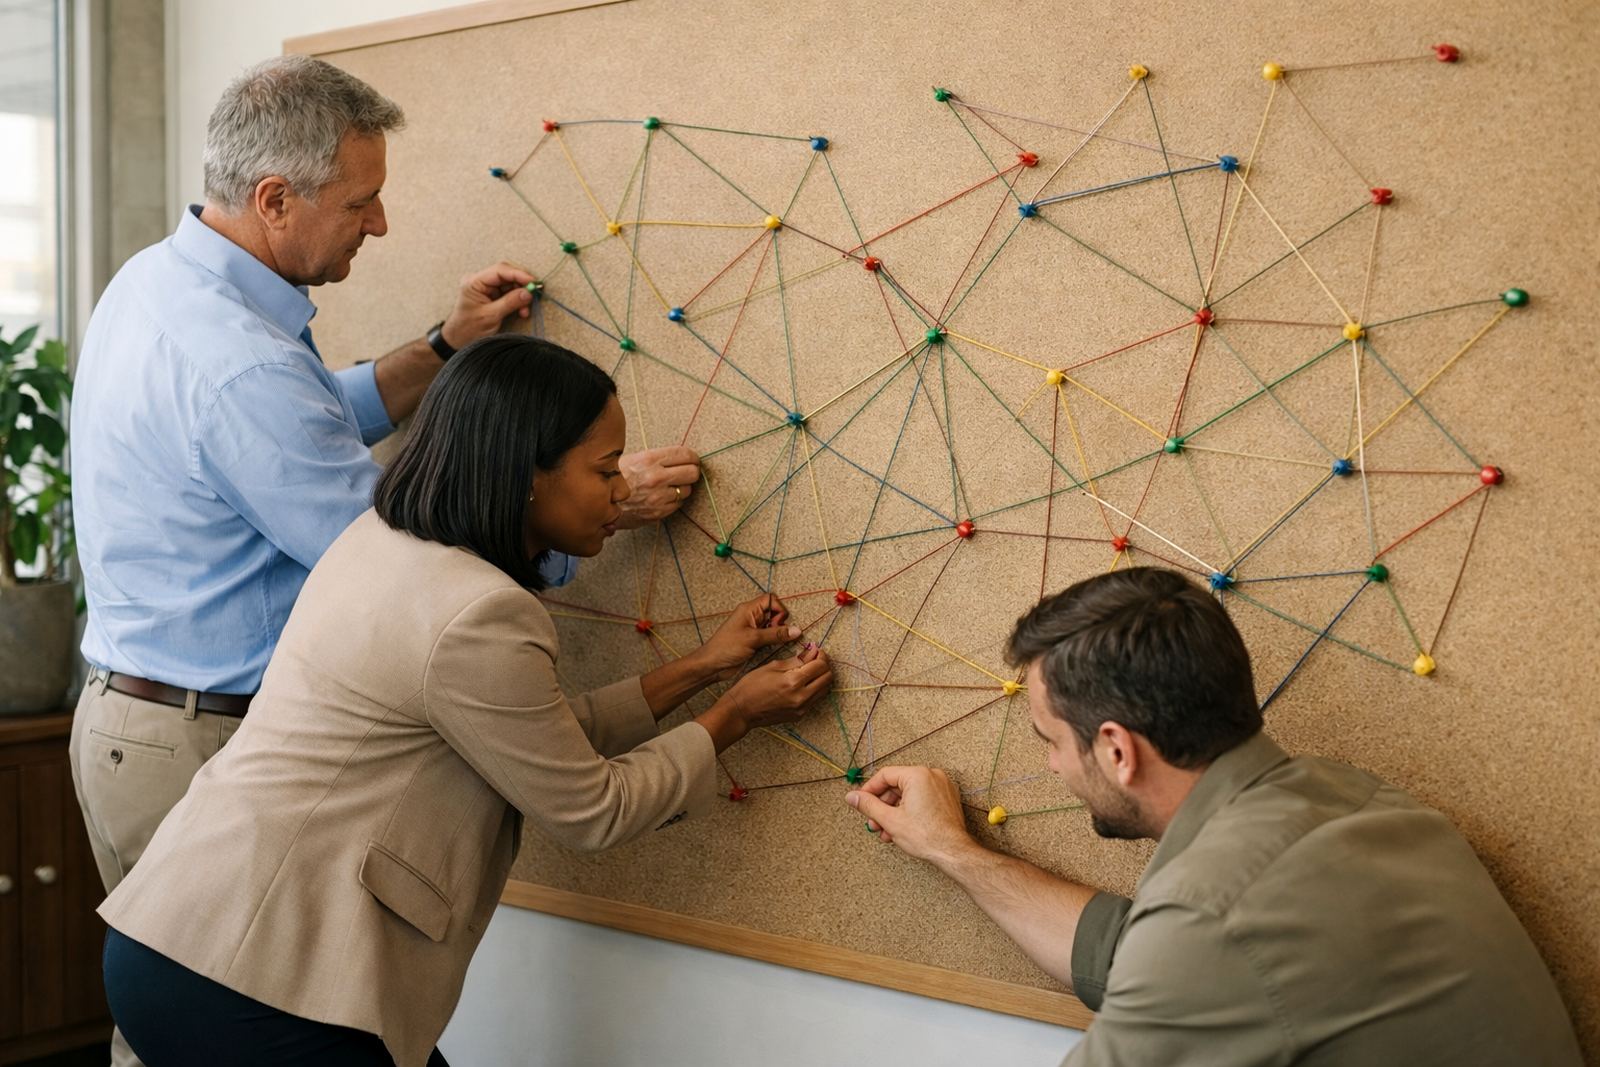
An asset map is not a fancy spreadsheet for the sake of it. It is a practical view of every asset, account, policy and liability linked to a person, a trust or a family business. When that picture is in one place, it becomes much easier to see where ownership sits, where nominations are outdated and where the estate may face delays.
For many families in Stellenbosch, Cape Town and Johannesburg, the first surprise is not the size of the estate. It is the number of moving parts. A home in one name, a business loan in another, a retirement annuity, shares in a private company, a trust deed, life cover and a property held with siblings can all sit in different places. Without mapping them, a family may think the plan is sorted when it is not.
An effective asset map usually records the asset, owner, beneficiary or nominee, location, supporting documents and any known risks. That gives the adviser and the family a clean starting point for estate planning, trust structuring and retirement income decisions.
Why families need visibility before they need solutions
People often ask for a will update first, or a trust review first. Those are important steps, but the real value starts with visibility. If you do not know what is owned, how it is owned and who depends on it, then even a well written will can leave gaps.
This is especially true where business owners are involved. A shareholder loan, suretyship or buy and sell arrangement can carry more weight than the family home, yet it is often overlooked. In a family where the income comes from a small company, one missing document can delay access to cash when it is needed most.
- It helps identify assets held in personal names, trust names and company names
- It shows whether beneficiary nominations match the current family position
- It highlights assets that may take time to realise, such as property or business interests
- It makes it easier to check whether there is enough liquidity for estate costs and tax
- It reduces confusion for children, spouses and executors after a death
The South African realities that make mapping essential
South African estates have their own practical issues. Load-shedding can interrupt admin and delay signatures. Coastal humidity in Durban can affect paperwork that is stored poorly. Municipal rates, body corporate levies and transfer costs can continue running while a family is still trying to gather records. If the map is incomplete, those day to day costs can catch people off guard.
There is also the question of succession. A family business in Paarl may be tied to one person’s bank account, while the shares sit elsewhere. A house in Claremont may be occupied by one family member, but owned jointly. A trust may hold assets for minor children, yet the trustees are not sure who should brief the next generation. Mapping these details early gives everyone a clearer path.
When done properly, the map is not just a list. It becomes the backbone of the estate file, the trust file and the family conversation.
How Pass It On Create uses the map in planning
At Pass It On Create, the asset map is the starting point for calm, structured advice. It helps the team see how estate planning, will coordination, trust structuring and retirement income planning fit together. The point is not to sell more products. The point is to understand the family position properly before decisions are made.
For business owners and multi-generational households, this often includes family meetings, trustee briefings and succession facilitation. A useful map can show where a trust supports long term continuity, where personal ownership creates risk and where liquidity may be needed to settle costs without forcing a quick sale.
- Estate Planning and Will Coordination for clearer instructions
- Trust Structuring where assets need careful separation
- Retirement Income Planning for owners who still support dependants
- Beneficiary Reviews to keep records current
- Liquidity Analysis to test whether cash will be available when needed
A local example from the Western Cape
Consider a Stellenbosch family with a mother, two adult children and a small wine related business. The mother owns the home, the business shares, a retirement annuity and a rental flat in Somerset West. One child lives in Johannesburg, the other helps with the business from Cape Town. On paper, the family says the estate is simple. Once the asset map is done, the picture changes.
The rental flat has an old beneficiary nomination that no longer matches the will. The business depends on the mother’s suretyship, which was never revisited after the children started working in the firm. The retirement savings will not settle all the costs and there is not enough liquid cash to cover transfer costs, executor fees and a few months of business overheads. None of this is unusual, but all of it matters.
With that map in hand, the family can decide what should be updated now, what should move into trust, and what needs a proper succession conversation. That is how an abstract plan becomes a practical one.
What should be checked every year
An asset map is not a once off exercise. Families change, businesses change and documents go out of date. A yearly review is usually enough for most households, though a major life event should trigger an earlier update.
Useful review points include marriage, divorce, a new child, a home purchase, a business sale, retirement, death in the family or a move between provinces. For clients who consult online from Durban, Cape Town, Johannesburg and beyond, a remote review can still be thorough if the records are organised and the right questions are asked.
- Is the owner name still correct on each asset?
- Do wills and nominations still match the current family structure?
- Are trustees, executors and signatories still suitable?
- Is there enough liquidity for estate costs and short term cash flow?
- Have any loans, guarantees or dependants been missed?
A clear map makes handover easier
Families do not usually struggle because they lack goodwill. They struggle because the details are scattered. An asset map brings those details together so the next step is easier to see. It helps protect dignity, reduce conflict and keep decisions practical when emotions are high.
That is the real value. Not paperwork for its own sake, but a fair and organised handover. When every asset, owner and link is visible in one place, the family can act with purpose instead of guesswork.