When a family has more than one branch
Blended households often come with good intentions and difficult questions. There may be children from a previous relationship, a current spouse, stepchildren, maintenance commitments, a family business, and property in more than one name. In Cape Town, Stellenbosch, Paarl, Johannesburg and Durban, we see the same pattern: the family wants fairness, but nobody wants conflict later.
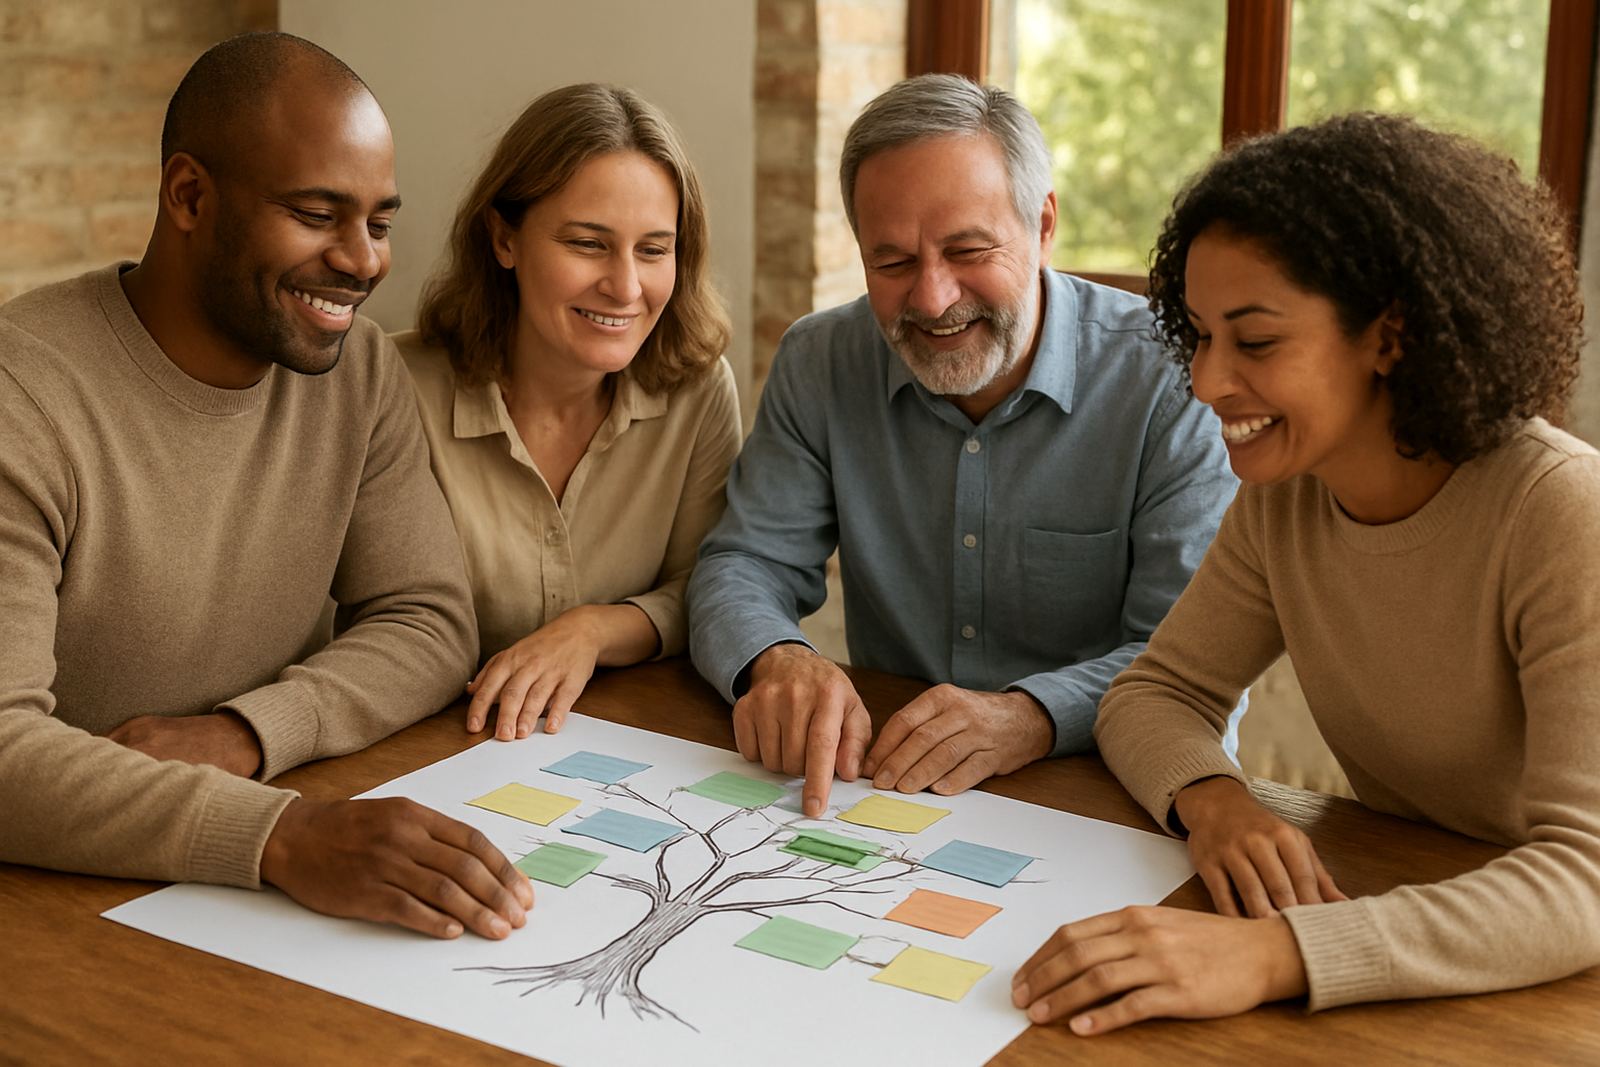
Our role is to help families put the full picture on paper before a crisis. That means mapping who depends on what, what assets are liquid, where ownership sits, and where a will on its own may not be enough. A calm process helps people speak honestly about housing, education costs, retirement needs and what happens if one partner dies first. It is not always neat, but it can be clear.
Blended families usually need planning that makes room for dignity, not assumptions. A spouse may need to remain in the home, while adult children need certainty about inheritances. In practice, the plan has to work on paper and in real life too, otherwise it can lead to delays, disputes and extra legal cost.
The planning set we usually work through
Every household is different, but the starting point is usually the same set of documents and decisions. We review the current will, beneficiary nominations, trust documents if any, ownership records, loan accounts, retirement benefits, and any business agreements that affect succession. In some homes, a family meeting is the best way to gather the information. In others, we begin with one or two private conversations first.
- Wills for each adult with wording that matches the family structure
- Trust structures where minor children, vulnerable beneficiaries or long term assets need protection
- Beneficiary reviews on retirement funds and policies
- Asset mapping for the home, investments, business interests and vehicles
- Liquidity analysis to check whether the estate can settle debt, tax and admin costs
Where there is a business, we also check whether buy-sell arrangements, shareholder agreements or succession clauses are aligned. A family can have a strong estate plan but still face trouble if the business side is ignored. That gap is more common than people think.
How to structure fairness without forcing sameness
Fairness is not always equal shares. In blended households, one child may still be at school, another may already be established, and a surviving spouse may need the home and income first. The aim is to make the plan fair in context, not just mathematically equal. That is where careful drafting matters.
We often help families think through three layers: immediate needs, medium term support, and long term inheritance. A surviving spouse may need access to income and housing, while children from an earlier relationship may need certainty that their eventual share is protected. If there is a trust, the trustees must understand the limits of their power and the duties they carry. This is not the place for vague promises or casual family understandings.
A useful rule is to decide early what must be fixed and what can remain flexible. Fixed items may include who gets the house, who receives cash, and how school fees or care costs are handled. Flexible items may include the timing of distributions or how investment income is used. This kind of structure reduces pressure on the family at the worst time.
Common mistakes we see in blended families
Many problems begin with silence. Couples assume they are on the same page, then discover they are not when illness or death happens. Another common mistake is leaving everything to the surviving spouse and trusting they will "do the right thing" later. That can be reasonable in some homes, but it can also leave children exposed if the survivor remarries or changes their own will.
- Not updating beneficiary nominations after remarriage or the birth of a child
- Using a basic will where a trust or layered structure is needed
- Forgetting debt, estate duty, transfer fees or executor costs
- Assuming stepchildren inherit automatically
- Leaving property in joint names without checking the consequences
We also see families underestimate how much admin matters. If documents are old, unsigned, or inconsistent, the estate can stall. On the practical side, a family in coastal areas like Durban or Somerset West may also want to keep records in order because humidity and load-shedding can expose weak document storage habits. A fireproof safe and clean copies are simple, but useful.
What a practical plan looks like in Rand terms
Planning fees are usually modest compared with the cost of a dispute, but the budget depends on complexity. A simple will review may start from around R1 500 to R3 500 per adult. A fuller estate plan with family meetings, beneficiary reviews and asset mapping can sit in the region of R5 000 to R15 000 for a household. Where trust structuring, succession facilitation and liquidity analysis are needed together, the work can range from R15 000 to R45 000 or more, depending on the number of entities and assets.
For households with business interests, multiple properties, offshore links or a blended family with dependants in different homes, the process usually takes more time. That extra work is there to avoid later cost. It is often better to spend carefully now than force the estate to pay for confusion later, which can become very expensive. In Johannesburg and Cape Town especially, property values can make even small drafting mistakes costly.
We prefer to sequence the work in a sensible order: first the facts, then the structure, then the documents. If needed, we can meet in Stellenbosch, Cape Town, Paarl, Johannesburg or Durban, and we also offer video consultations nationwide. Some clients want one family meeting with everyone in the room. Others prefer separate sessions first so each person can speak freely. Both can work well.
How we guide the conversation in the right order
Blended household planning is not only a paperwork exercise. It is also a conversation about values, expectations and timing. We help families move from uncertainty to a plan that is specific enough to guide action, but flexible enough to handle real life. That includes retirement income planning for the surviving spouse, succession facilitation for business owners, and legacy workshops where the next generation can understand the thinking behind the structure.
The best outcomes usually come when the family accepts that every branch matters. That does not mean every person gets the same thing. It means each person is considered properly, and the plan reflects the reality of the household. When that happens, the result is usually calmer, cleaner and easier to carry forward.
If you are balancing children from different relationships, a current spouse, a family business and property in more than one place, the sooner the plan is tested the better. Small decisions made now can prevent big tensions later, and that is often where real peace starts.